All Eyes on Washington as July’s Inflation Numbers Arrive
The country’s attention turns to economic data this morning as the Bureau of Labor Statistics releases its Consumer Price Index reading for July, a report that has taken on outsized importance for households, investors, and the Federal Reserve alike. Due out at 8:30 a.m. Eastern, the release will offer the clearest signal yet of whether the recent surge in oil prices tied to the Middle East conflict is beginning to bleed into broader consumer costs.
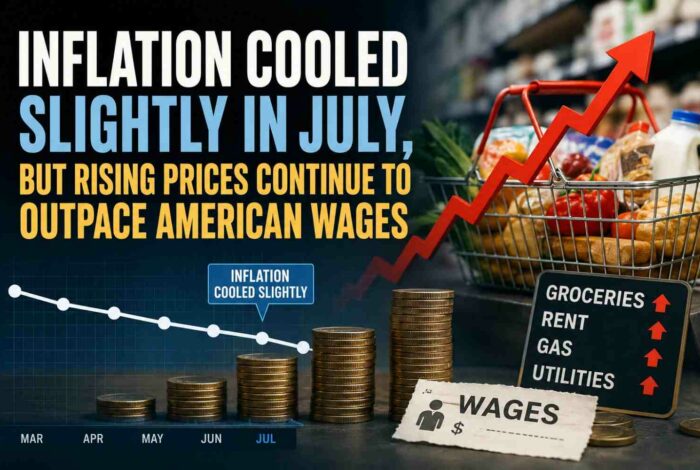
Economists surveyed ahead of the release generally expect headline inflation to ease slightly on an annual basis, with some forecasts pointing to a year-over-year figure near 3.4%, down modestly from June’s 3.5% pace. Core inflation, which strips out volatile food and energy costs, is projected by several Wall Street banks to come in around 2.5% annually, which would mark its softest reading since the start of the year.
Why This Report Carries Extra Weight
Unlike routine monthly releases, this month’s CPI print is being watched as a pivotal input for the Federal Reserve’s next policy meeting in September. Fed Chair Kevin Warsh has faced growing pressure from both directions: softer hiring data has strengthened the case for additional rate cuts, while a summer spike in oil prices — up roughly 21% in July alone amid the Iran-related conflict — has revived worries that inflation could reaccelerate.
Long-term inflation expectations, as measured by Treasury swaps markets, continue to sit above the Fed’s 2% target, hovering near 2.4%. Meanwhile, yields on 30-year Treasury bonds have climbed to levels not seen in roughly two decades, a sign that bond investors are demanding more compensation for the risk that inflation stays elevated for longer than hoped.
Several major banks have offered their own previews of what today’s numbers might show. Forecasts point to headline CPI rising modestly on a monthly basis, helped along by softer gasoline prices earlier in the survey period, while core goods prices are expected to stay subdued and core services costs, particularly shelter, are expected to tick back up after a milder reading in June.
The Oil Price Wildcard
The unresolved standoff over the Strait of Hormuz looms large over today’s release and, more importantly, over the readings still to come. Because July’s survey period captured only part of the recent run-up in crude prices, several economists caution that the true inflationary impact of the energy shock may not be fully visible until the August and September reports. If the standoff at Hormuz persists and oil prices remain elevated, pressure on transportation costs, shipping, and eventually consumer goods could build in the months ahead.
That dynamic has made this month’s release something of a preview rather than a final verdict. Investors are bracing for the possibility that a relatively tame July number gives way to hotter readings later in the year if energy costs stay elevated, which would complicate the path toward further rate cuts that markets had been pricing in earlier this year.
What It Means for Households
For everyday consumers, the report offers a mixed picture. Falling gasoline prices earlier in the summer provided some relief at the pump, but shelter costs — which include rent and the imputed cost of homeownership — remain one of the largest and stickiest contributors to the overall index. Grocery prices have also shown more volatility than usual, driven in part by seasonal factors and lingering effects from tariff policy adjustments enacted earlier in the year.
Small businesses, meanwhile, appear cautiously optimistic. A recent survey from the National Federation of Independent Business showed its Small Business Optimism Index climbing to its best level in roughly a year, with a rising share of owners saying they plan to add jobs in the coming months — a signal that Main Street sentiment has held up better than some economists expected, even amid broader uncertainty.
The Path Ahead
Markets will be parsing today’s release for clues not just about where prices stand now, but about the trajectory the Fed is likely to follow at its September meeting. A cooler-than-expected core reading could reinforce expectations for continued rate cuts, while a hotter print — especially one showing early signs of energy-driven pass-through — could tilt the debate toward a pause or even a hike. Either way, with the Iran conflict still unresolved and oil markets on edge, today’s numbers are unlikely to be the last word on where inflation is headed this year. Next Article